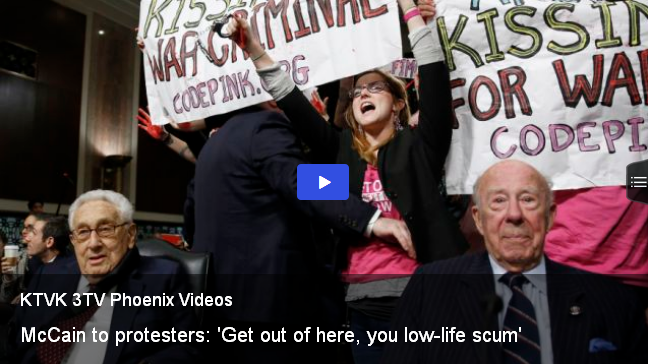Showing posts with label Bankrupting the Common People. Show all posts

December 3, 2020

Biden Supports a Global Tax That Could Affect the Stocks, Mutual Funds, and Pensions of Ordinary Americans

Obama, Global Taxes and the Millennium Development Goals

September 16, 2010

Canada Free Press - In a classic case of misdirection, while the media are preoccupied with the fate of the Bush tax cuts, President Obama is preparing to attend a United Nations summit next week to endorse “innovative finance mechanisms”—global taxes—to drain even more wealth out of the U.S. economy.

A draft “outcome document” produced in advance of the September 20-22 U.N. Summit on the Millennium Development Goals (MDGs) commits the nations of the world to supporting “innovative financing mechanisms” to supplement foreign aid spending.

The term “innovative financing mechanisms” is a U.N. euphemism for global taxes. But the document actually goes further, praising the “Task Force on International Financial Transactions for Development” for its work on the subject of mobilizing additional “resources” for countries to achieve the MDGs. This is a body tasked with proposing and implementing global tax schemes.
“We consider,” the document says, “that innovative financing mechanisms can make a positive contribution in assisting developing countries to mobilize additional resources for financing for development on a voluntary basis. Such financing should supplement and not be a substitute for traditional sources of financing.”
In other words, the revenue from global taxes should be in addition to foreign aid spending.

The document recognized the “considerable progress” made in this area, an acknowledgement that an international tax by some nations on airline tickets is already in effect and producing several billions of dollars of revenue for world organizations to fight AIDS and other diseases.

In an article in The Christian Science Monitor, under the headline,
“Small global taxes would make a big difference for world’s ‘bottom billion’,” the foreign minister of France and other officials of foreign nations endorse various forms of “innovative development financing.”
One of their proposals is a tax on international currency transactions that could generate $35 billion a year.

The proposal, popular at the United Nations for decades and long-advocated by Fidel Castro, is called the Tobin Tax and named after Yale University economist James Tobin. Steven Solomon, a former staff reporter at Forbes, said in his book, The Confidence Game, that such a proposal “might net some $13 trillion a year…” because it is based on taking a percentage of money from the trillions of dollars exchanged daily in global financial markets.

He is referring to the fact that once such a tax is in place, it could be easily raised to bring in hundreds of billions of dollars or more a year to the U.N. and other global institutions.

Such financial transactions through banks and other financial institutions are commonplace on behalf of Americans who have stock in mutual funds or companies that invest or operate overseas. Hence, such a global tax could affect the stocks, mutual funds, and pensions of ordinary Americans.

The term “small global taxes” brought a stunned reaction from Senator David Vitter, when he was told of what is being proposed in advance of the U.N. summit. Vitter introduced Senate resolution 461, “Expressing the sense of the Senate that Congress should reject any proposal for the creation of a system of global taxation and regulation,” to put the Senate on record against any such measure. He has vowed to maintain pressure on the world body to avoid implementing any of these schemes and thinks that the Congress has to use whatever financial leverage it has to frustrate U.N. demands for more power and authority in world affairs.

The Vitter resolution was sent to the liberal-controlled Senate Finance Committee, which declined to act on it.

Obama has been a major U.N. supporter since he was in the Senate and sponsored a bill, the Global Poverty Act (S 2433), to force U.S. compliance with the MDGs. Joseph Biden, then chairman of the Senate Foreign Relations Committee, tried to get it passed into law but ultimately failed.

As President, Obama is in a position to actively promote global taxation measures and clearly has done so. The “outcome document” his administration has already endorsed will be formally approved at next week’s summit.

The document affirms the so-called “Monterrey Consensus” that committed nations to spending 0.7 percent of Gross National Product (GNP) on official development assistance (ODA), otherwise known as foreign aid.
It says that “The fulfillment of all ODA commitments is crucial, including the commitments by many developed countries to achieve the target of 0.7 percent of gross national product (GNP) for ODA to developing countries by 2015…”
Over a 13-year period, from 2002, when the U.N.’s Financing for Development conference was held, to the target year of 2015, when the U.S. is expected to meet the Millennium Development Goals, this amounts to $845 billion from the U.S. alone, according to Jeffrey Sachs of the U.N.’s Millennium Project.
“We have fully embraced the Millennium Development Goals,” Obama told the U.N. in 2009.


Read more here and here.

April 7, 2017

The IRS Has Been Quietly Confiscating Millions from Honest Small Business Owners

April 6, 2017

() - Brothers Jeffrey, Richard, and Mitch Hirsch have owned Bi-County Distributors, Inc., in Ronkonkoma, New York, for 27 years.

When Mitch Hirsch went to the bank in May 2012, the teller delivered some unexpected news: the bank account he and his two brothers, Jeff and Richard, used to deposit the proceeds from their convenience store distribution business had been commandeered by the federal government.

Later that day, Mitch’s older brother Jeff got a letter from the IRS; it explained that the brothers’ pattern of making frequent and small deposits had drawn suspicion. The Hirsch brothers did business with small delis and gas stations, and often made cash deposits in their account. But the IRS apparently mistook these transactions for the behavior of a drug dealer or a terrorist trying to fly below the radar.

Mitchel’s older brother Jeff called the local joint-IRS task force in Nassau County, New York to clear up the misunderstanding. He even invited the detective in charge to come down to his warehouse and go through his business records. The detective, Jeff said, explained that it wasn’t his job to investigate any further — the pattern of deposits was all the evidence he needed.  

The brother were never charged with a crime or accused of any wrongdoing. But it cost them tens of thousands of dollars, and over two years of fighting the IRS in court, to finally get the money returned.
“It was hell,” Jeff said. If it wasn’t for a the generosity of a friend who works in the candy distribution business — who let the brothers slide on a few late payments — Jeff said that his entire family would have gone bankrupt.  

The Hirsch brothers’ ordeal is far from uncommon, according to a March 30 report from the Treasury Inspector General For Tax Administration (TIGTA), a government watchdog that oversees the IRS. Between 2012 and 2014, the IRS seized over $17 million from hundreds of small business owners like the Hirschs — whose only “crime” was making frequent cash deposits and withdrawals of under $10,000, which isn’t technically a crime at all.

Banks must report to the IRS all individual deposits, withdrawals or transfers of over $10,000; it’s illegal for anyone to structure multiple transactions of $10,000 or more in order to evade IRS attention, and banks are required to report if they think their customers are making many under-limit transactions to avoid triggering notification.

Still, drug dealers and other criminals often do to attempt to stay below the radar of law enforcement; former House Speaker Dennis Hastert was ensnared by the law (and pled guilty to violating it) when he made under-limit withdrawals to pay a man who had accused Hastert of sexual assaulting him. But, it’s also perfectly normal for small and medium-size business owners to make regular deposits under the $10,000 mark. In the Hirsch case, the brothers’ insurance company had actually asked them to make smaller deposits, Jeff Hirsch says, after they had been robbed on the way to the bank.

Federal law allows the IRS to freeze anyone’s assets it suspects of making evasive deposits, without requiring that they secure a criminal conviction or even conduct an investigation beyond examining the bank records. In other words, the IRS can — and does — empty some people’s bank accounts simply because the owners make deposits that fit a pattern that the government believes may resemble that of a drug dealer.

“They are supposed to be targeting people hiding criminal proceeds,” explained Robert Johnson, an attorney with the libertarian-leaning Institute for Justice who represented the Hirsch brothers. “But they are applying it to people who engaged in perfectly legal businesses.” The Institute has represented a number of people, including a Palestinian immigrant deli owner and a restaurateur in North Carolina, who all had to spend years fighting the IRS just to get their legally-acquired money back.

In one case, the IRS seized $33,000 from Carole Hinders, who had operated a small cash-only restaurant for 40 years in Arnold’s Park, Iowa, and made routine small deposits. “My mom had told me, if you keep your deposits under $10,000, the bank avoids paperwork,” she told the New York Times. “I didn’t actually think it had anything to do with the I.R.S.” In another instance, North Carolina convenience store owner Lyndon McLellan lost over $100,000 when the IRS seized his bank account in the summer of 2014.

“It took me 13 years to save that much money, and 13 seconds for the government to take it away,” he told the Washington Post.

And it’s not just that the IRS occasionally seizes the assets of innocent business owners by mistake and is unaware of the problems with its methodology: According to the TIGTA report, the IRS almost always misses the mark. The watchdog randomly selected 278 different cases in which the IRS emptied a bank account because it suspected illegal transaction structuring. In a full 91 percent of those cases, it turned out that the IRS had taken money from perfectly legal small businesses — farms, convenience stores, restaurants — that just so happened to withdraw money from the bank in a pattern that caught authorities’ attention.

“Most people impacted by the program did not appear to be criminal enterprises engaged in other alleged illegal activity,” the inspector general found, “rather, they were legal businesses such as jewelry stores, restaurant owners, gas station owners, scrap metal dealers, and others.”

In a response to the watchdog report, the IRS emphasized that it had been acting within the law. “Structuring violations are not required to be tied to illegal source funds,” wrote Richard Weber, the chief of criminal investigations at the IRS.

February 12, 2017

The Most Vocal Outcries Against Trump Come from Urban Elites and the Corporations That Cater to Them

Elites Protest a New Revolution

“We deserve to be in in charge.” 

February 6, 2017

Daniel Greenfield - The revolution will not be brought to you by Xerox. It will be brought to you by BMW. The German luxury automaker is a key advertiser at GQ. And GQ is the headquarters of the Resistance. That's a vlog by Keith Olbermann who returned from his exile at an ESPN Elba to denounce Trump.

"I am Keith Olbermann," Keith Olbermann barks to the peasants and workers of GQ who are taking a break from reading an article on '$100 Cologne that Smells Like Nothing', "This is the Resistance."

The Resistance is Remy Martin and Coach. It’s the ‘Best Silver Nail Clippers for Men to Buy Now’ and ‘7 Skincare Treatments Men are Asking for in 2017’. It’s the SAG Awards and the Golden Globe Awards.

It’s the self-important people and the beautiful people rising up against the democratic oppression of the working class and proclaiming courageously in one voice, “We deserve to be in in charge.”

When the revolution isn't at GQ (The Most Radical Dress Socks to Wear Right Now), it's at Vanity Fair where Graydon Carter denounces Trump (Donald Trump: A Pillar of Ignorance and Certitude) with a byline photo of himself taken by Annie Leibovitz smiling smugly from his skyscraper office.

Maybe the resistance is Reed Hastings, the billionaire CEO of Netflix, who used his wealth catering to the tastes of urban elites, to lobby to raise the taxes of the middle class. Hastings whined that President Trump's moves to protect Americans were "so un-American it pains us all.”

Who are these 'us'? It might be Warren Buffett, Google's Eric Schmidt and Facebook's Sheryl Sandberg, with whom Hastings had joined to support Hillary Clinton. Or it might be the CEOs of Lyft, Airbnb and Twitter, to name a few, who have jointed the anti-Trump “resistance” of wealthy elites.

It's no coincidence that the most vocal outcries against President Trump's measures have come from urban elites and the corporations that cater to their whims. It's easy to spot the class divides in the scoffing at Andrew Puzder, CEO of the company behind Carl's Jr. and Hardee's, getting a cabinet position instead of Facebook's Sheryl Sandberg who had been  tipped for Treasury Secretary by Hillary.

Carl's Jr and its 4 Dollar Real Deal are a world away from Facebook's Gehry designed Menlo Park headquarters. As much as a WWE tournament is from Conde Nast's Manhattan skyscraper.

It's hard to imagine a clearer contrast between coastal elites and the heartland, and between the new economy and the old. On the one side are the glittering cities where workforces of minorities and immigrants do the dirty work behind the slick logos and buzzwords of the new economy. On the other are Rust Belt communities and Southern towns where working people actually used to make things.

Facebook's top tier geniuses enjoy the services of an executive chef, treadmill workstations and a bike repair shop, all walled off from East Palo Alto's Latino population and its crime and gang violence. But who works in Facebook's eleven restaurants or actually repairs the bikes in the back room? Or looks through the millions of pictures posted on its timelines to screen out spam, pornography and violence?

Behind the illusion of a shiny new Facebook future are Mexicans getting paid a few dollars an hour to decide if that Italian Renaissance painting you just shared violates its content guidelines.

If you live in the world of Facebook, Lyft, Netflix and Airbnb, crowding into airports and shouting, "No Borders, No Nations, Stop The Deportations" makes sense. You don't live in a country. You live in one of a number of interchangeable megacities or their bedroom communities. Patriotism is a foreign concept. You have no more attachment to America than you do to Friendster or Myspace. The nation state is an outdated system of social organization that is being replaced by more efficient systems of global governance. The only reasons anyone would cling to nations and borders are ignorance or racism.

The demographic most opposed to President Trump is not a racial minority, but a cultural elite.

This isn't a revolution. The revolutions happened in June and November. Brexit and Trump were revolutions. The protests against them are a reaction by the overthrown establishment.

January 22, 2017

Taxes, Chicago-Style

City Of Chicago Bag Tax - Goes In Effect February 1, 2017

Edtior's Note: This is not a price charged by the store for a bag but a tax applied by the city to each bag that a store uses to bag your purchases, which is payable to the city of Chicago.

To encourage customers to bring their own reusable bags, the City of Chicago is implementing a $.07 tax on each paper and plastic bag provided by stores to customers to carry out purchased items.  Businesses will start collecting the tax on February 1, 2017.

Some exemptions, include:

Paper and Plastic bags used to package loose bulk items, such as fruit, vegetables, nuts, grains, candy, cookies, or small hardware items or to contain or wrap frozen foods, meat or fish, whether prepackaged or not.

Bags Provided by a pharmacist to contain prescription drugs, dry cleaning, or garment bags and newspaper bags.

Bags sold in packages containing multiple bags intended for use as garbage bags, pet waste bags or yard waste bags.

Bags provided by a dine-in or take-out restaurant to contain food or drink purchased by the restaurant's customers.

It is a good time to start the new habit now.  Take your bags to the store with you!

Paper and Plastic bags used to package loose bulk items, such as fruit, vegetables, nuts, grains, candy, cookies, or small hardware items or to contain or wrap frozen foods, meat or fish, whether prepackaged or not.

For more information, visit: https://www.cityofchicago.org/city/en/depts/fin/provdrs/tax_division/news/2016/december/NewCheckoutBagTax.html

Chicago property tax bill double whammy: Increases plus an assessment hike

August 1, 2016

November 18, 2016

November 18, 2016

CNS News - The United Mine Workers of America—a roughly 100,000-member coal mining union—is lobbying hard for a taxpayer bailout of its underfunded pension plan before the end of the year. And it’s already well on its way.

The Senate Finance Committee passed S.1714, the Miners Protection Act, out of committee on Sept. 22.
The UMWA’s pension plan for coal miners is vastly underfunded. It has less than half the money it needs to pay promised benefits and is projected to run dry by 2025. Despite this mismanagement, the UMWA has also managed to provide its officers and non-coal worker employees with a pension that is 100 percent funded.

If the UMWA was able to secure a healthy pension fund for itself, how did it end up pushing the pensions of nearly a 100,000 coal miners to the point of no return?

The UMWA’s first and fatal mistake was fighting vehemently to pay pension benefits to workers who did not earn them. Almost immediately after the plan was launched, it started paying benefits to retired workers who had never accumulated pension contributions. This put the pension plan off kilter from the start.

The UMWA’s second failure was consistently promising significantly larger benefits than could be supported by employers’ contributions. The UMWA’s plan did this by assuming unrealistic investment returns.
While non-union private pension plans must use a government-prescribed and realistic interest rate, unions enjoy regulatory favoritism that allows them to use whatever interest rate assumptions they want when running their pension plans.

By exploiting unreasonably high interest rate assumptions, the UMWA plan trustees (made up of equal representation from the UMWA and coal industry representatives) created a win-win for themselves: The UMWA delivered significant pension benefit promises for its members, and coal industry employers did not have to contribute enough to actually fund those promises.

The losers will be UMWA members and the taxpayers who could end up supplying the bailout.

The UMWA puts most of the blame for its pension failure on the massive decline of the coal industry. But if a plan is properly funded from the start and appropriately managed along the way, it wouldn’t matter if the entire coal industry were wiped out—the benefits workers had already earned would still be there.

November 10, 2016

Saul Alinsky Would Be Proud of the Radicals in Large U.S. Cities: University Administrators and Professors and High School Teachers Postponed Tests and Organized Civil Disobedience; Protestors Set Fires, Obstructed Traffic, and Burned U.S. Flags and an Effigy of Trump (Imagine the Mayhem That Would Have Ensued Had Someone Burned an Effigy of Obama in 2008 or 2012)

November 10, 2016

USA TODAY - Protesters took to the streets Wednesday in at least 10 cities to march against president-elect Donald Trump - and numerous college students and faculty leaders took to social media to announce support groups and even postponed exams.

Protests were underway in Chicago, New York, Los Angeles, Philadelphia, Boston, Washington, D.C., Portland, Ore., St. Paul, Minn. and several other cities. An estimated 2,000 protesters shouted angrily in downtown Seattle, expressing their frustration at the Trump victory over Democrat and former Secretary of State Hillary Rodham Clinton, who won 228 electoral votes to Trump's 279.

Police in riot gear struggled to hold back scores of protesters in some of the cities as protesters chanted "Not My President" and "No Racist USA." The protests were mostly peaceful. Seattle police said they were investigating a report of a shooting near the site of the protest in that city, but it may not have involved protesters.

In Los Angeles, protesters poured into the streets near City Hall and torched a giant Trump effigy, the Los Angeles Times reported. Later in the night, hundreds marched onto the busy 101 Freeway which brought the highway to a complete standstill. The California Highway Patrol and the Los Angeles Police Department —who urged protesters to remain lawful and peaceful — responded and were seen leading demonstrators away from the busy highway.  At least 13 people were later arrested, LAPD Officer Tony Im told the Los Angeles Times.

In Washington, D.C., hundreds took to the streets carrying signs saying “Nasty Women Fight Back” and “White Males for Equality for All.”

The unrest culminated when two separate anti-Trump demonstrations converged in front of the Trump International Hotel. They chanted and yelled "Impeach Donald Trump” and toward the end yelled at police officers who stood guard at the hotel entrance.
In New York, thousands of demonstrators blocked off streets around Trump Tower near the busy intersection of 57th Street and Fifth Avenue, chanting "hey hey, ho ho, Donald Trump has got to go" and "p---y grabs back," a reference to taped conversations of Trump making lewd commentary about women. One woman protester was topless while another climbed on top of a tree to see the activity. Taxis, city buses and passenger vehicles stood at a standstill.

"We're (mad) so we're out here in the streets," said demonstrator Omar Aqeel, a 27-year-old film producer who lives in Brooklyn.

While he and other demonstrators said they were aware that protests could not reverse the election, they said they still felt it would have an effect on the future.

"I hope it rallies everyone together as a wake up call," Aqeel said.

"I think there's a chance for impeachment at the end of the day," said protester Joey Henriquez, a 22-year-old student at the City College of New York, who lives in Manhattan. "We can't let him have eight years."

In Boston, thousands of anti-Donald Trump protesters streamed through downtown, chanting "Trump's a racist" and carrying signs that said "Impeach Trump" and "Abolish Electoral College."
In Chicago, several hundreds of protesters gathered near the Trump International Hotel and Tower to express their displeasure with the president-elect.

The protesters held signs with messages such as "Love Trumps Hate," "Not My President " and expletive-laden repudiations.

Chloe Stratton, 33, a transgendered woman who moved to Chicago earlier this year, said she fears for what a Trump-Pence White House holds for the nation's LGBT community.

Pence has opposed same-sex marriage and expressed support for shock therapy for people with same-sex attractions.

"I am terrified for my life," said Stratton, who added that she has begun exploring options to move away from the U.S.

Police said five people were arrested in Chicago over the course of the protest on minor charges—two for obstructing traffic, one for criminal trespass, one for reckless conduct, and one for criminal trespass and resisting arrest.
Just last week, the Democrat-controlled Chicago's city council voted to remove honorary signage near Trump's building, a rebuke for the president-elect's blistering criticism of crime in the city while he was on the stump.

On Wednesday, Mayor Rahm Emanuel insisted he did not fear that Trump would exact any payback on the city over the move.

"I'm not worried about Donald Trump trying to somehow penalize Chicago, " said Emanuel, who served as President Obama's first White House chief of staff.

Earlier Wednesday, protesters at American University burned U.S. flags on campus.

In Oregon, dozens of people blocked traffic in downtown Portland, burned American flags and forced a delay for trains on two light-rail lines. Trump supporters taunted the demonstrators with signs.  At one point, a lone Trump supporter was chased across Pioneer Courthouse Square and hit in the back with a skateboard before others intervened.
An estimated 6,000 protesters gathered Wednesday night in Oakland, Calif. Videos on social media captured fires erupting as the protests rolled on.

Across the country, universities and even a few high schools organized post-election civil disobedience of a different sort. Some teachers sent notes to students postponing tests and offering support. Student unions offered sessions of meditation, discussions and tea.

"The nation in which you currently reside decided last night to elect a president whose own words have painted him a moral and possibly physical hazard to many of us," University of Maryland professor Alan Peel wrote to students, postponing all assessments. "I debated whether to press on today in the spirit of re-establishing normalcy, but have come to realize that my position and my background may have afforded me the privilege to do so. Others may find they do not have that privilege."

"Partisan, inflammatory statements unfortunately seem to be part of modern campaign rhetoric, but they cause real wounds," Northwestern University wrote in an email to students Wednesday, reminding them to notify professors if they need to miss class. The email directed students to the campus Multicultural Center, the Gender & Sexuality Resource Center and The Black House, a gathering place for the university's black community. Throughout the day the campus hosted a “What’s Your Reaction” event for students to express themselves by drawing pictures. They even provided the paper, markers and snacks.
The University of California, Berkeley created safe spaces for minority students, and for those who might be illegal immigrants. There are also special "healing spaces" for women and those who identify as lesbian, gay, bisexual, or transgender.

"Be gentle with yourselves and take care of each other," according to an email sent to Berkeley students from four of the university's vice chancellors and others. "We know that the results of yesterday's election have sparked fear and concern among many in our community; in particular our immigrant and undocumented communities, Muslim, African American, Chicanx/Latinx, LGBTQ+, Asian and Pacific Islander communities, survivors of sexual assault, people with disabilities, women, and many others."

At the University of Vermont, administrators voiced a similar sentiment. "This is a challenging time for many of our colleagues and students, who may be feeling isolated and concerned for personal welfare," UVM president Tom Sullivan wrote in an email to the university community, offering time for tea and reflections, meditations and structured discussion.

The Boston Latin School, a high school in Boston, offered a support team of guidance counselors, clinicians, and nurses after school Wednesday and before school Thursday for students who need support, according to an email sent to the school community.

Montgomery Blair High School in Maryland had an election debriefing with counselors during students' lunch, according to a tweet sent by the school's principal.

2016 Election Results:


Source: USA TODAY

Trump won the election because:

October 18, 2016

October 18, 2016

WASHINGTON (AP) — Millions of Social Security recipients and federal retirees will get a 0.3 percent increase in monthly benefits next year, the fifth year in a row that older Americans will have to settle for historically low raises.

There was no increase this year. Next year's benefit hike will be small because inflation is low, driven in part by lower fuel prices.

The federal government announced the cost-of-living adjustment, or COLA, Tuesday morning. By law, the COLA is based on a government measure of consumer prices.

The COLA affects more than 70 million people — about 1 in 5 Americans.

The average monthly Social Security payment is $1,238. That translates into a monthly increase of less than $4 a month.

More bad news for seniors: Medicare Part B premiums, which are usually deducted from Social Security payments, are expected to increase next year to the point in which they will probably wipe out the entire COLA.

By law, the dollar increase in Medicare's Part B premium cannot exceed a beneficiary's cost-of-living raise. That's known as the "hold harmless" provision, and it protects the majority of Medicare recipients.
But another federal law says that the Part B premium must raise enough money to cover one-fourth of expected spending on doctors' services. That means that a minority of beneficiaries, including new enrollees and higher-income people, have to shoulder the full increase. Their premiums would jump.

Millicent Graves, a retired veterinary technician, says Medicare and supplemental insurance premiums eat up nearly a third of her $929 monthly Social Security payment. And don't tell the 72-year-old from Williamsburg, Virginia, that consumer prices aren't going up. She says her insurance premiums went up by $46.50 this year, and her cable TV, Internet and phone bill went up, too.

"I just lose and lose and lose and lose," Graves said.

More than 60 million retirees, disabled workers, spouses and children get Social Security benefits. The COLA also affects benefits for about 4 million disabled veterans, 2.5 million federal retirees and their survivors, and more than 8 million people who get Supplemental Security Income, the disability program for the poor. Many people who get SSI also receive Social Security.

Since 2008, the COLA has been above 2 percent only once, in 2011. It's been zero three times.

"This loss of anticipated retirement income compounds every year, causing people to spend through retirement savings far more quickly than planned," said Mary Johnson of the Senior Citizens League. "Over the course of a 25- or 30-year retirement, it reduces anticipated Social Security income by tens of thousands of dollars."

By law, the cost-of-living adjustment is based on the Consumer Price Index for Urban Wage Earners and Clerical Workers, or CPI-W, a broad measure of consumer prices generated by the Bureau of Labor Statistics. It measures price changes for food, housing, clothing, transportation, energy, medical care, recreation and education.

The COLA is calculated using the average CPI-W for July, August and September. If prices go up, benefits go up. If prices drop or stay flat, benefits stay the same.

The numbers for July and August suggest COLA of just 0.3 percent. The numbers for September are to be released Tuesday.

Some advocates complain that the government's measure of inflation doesn't reflect the costs many older Americans face.

For example, gasoline prices have fallen by nearly 18 percent over the past year, according to the August inflation report, while the cost of medical care has gone up by more than 5 percent.

For seniors who don't drive much, they don't get the full benefit of low gas prices, said Max Gulker, a senior research fellow at the American Institute for Economic Research. Many seniors, however, spend more of their income on health care.

Graves said she appreciates lower gas prices, but doesn't drive much.

"I just have to rely more each month on cashing in investments," Graves said. "I'm lucky I can do that."

Obama Sets 2017 Pay Raise for Civilian, Military Employees

What agency has the most employees? Which feds get paid the most? Federal News Radio looks at the latest data from the Office of Personnel Management.

August 31, 2016

FEDERAL NEWS RADIO - President Barack Obama is exercising his authority to give federal civilian employees and uniformed service members a pay raise effective Jan. 1, 2017.

Civilian employees will receive an across-the-board raise of 1 percent, with an additional 0.6 percent adjusted in locality pay.

“I have determined that for 2017, across-the-board pay increases will be 1.0 percent,” Obama wrote in an Aug. 31 letter to congressional leaders. “Also, I will make a decision by November 30, 2016, regarding an alternative plan for locality payments under 5 U.S.C. 5304a. The alternative plan for locality payments will be limited so that the total combined cost of the 1.0 percent across-the-board base pay increase and the varying locality pay increases will be 1.6 percent of basic payroll, consistent with the assumption in my 2017 budget. These decisions will not materially affect our ability to attract and retain a well-qualified federal workforce.”

Uniformed service members will also receive a monthly basic pay increase of 1.6 percent.

“This decision is consistent with my fiscal year 2017 budget. It will not materially affect the federal government’s ability to attract and retain well-qualified members for the uniformed services,” Obama wrote in a separate letter to congressional leaders.

The raise is just slightly above the 1.3 percent Obama approved last fiscal year.

April 28, 2016

Kroger Retirees May Be Trapped in a Pension Plan That is About to Cut Their Benefits Dramatically and Still Faces Likely Insolvency

Kroger employees sue over pension plan


Cincinnati Business Courier - A group of Kroger employees and retirees is suing an Illinois-based pension fund, claiming their retirement money has been mismanaged.

The lawsuit involves an underfunded pension plan called Central States, Southeast and Southwest Areas Pension Fund that holds about 5,000 current and retired Kroger Co. (NYSE: KR) employees’ retirement funds, according to the complaint filed in U.S. District Court in Illinois. The outside plan has lost assets over the years as fewer members contribute and thanks to investment losses. Kroger employees want out of the plan.

The 11 employees and retirees who filed the lawsuit call the pension plan “massively underfunded” and say it’s projected to be insolvent by 2026, according to the lawsuit. The plan has $17.8 billion in assets and $35 billion in promised investments.

The plaintiffs in the case live in Indiana, Michigan and Kansas. They worked at Kroger for decades. Many are retired but have gotten jobs to make up for lost pension benefits or are expecting to get jobs during their retirement.

One example of the pension plan’s reduction program would cut participants’ benefits by 31 percent to 71 percent.

The plan’s board filed an application with the U.S. Treasury Department in September to get approval to reduce benefits. The plan’s participants “face an imminent threat of draconian reductions in the future, followed eventually by the plan’s complete collapse,” the Kroger employees said in the lawsuit.

The plaintiffs are all current or former Kroger employees who are represented by the International Brotherhood of Teamsters. The Teamsters negotiated a plan to move Kroger participants to a new plan. It joined Kroger in asking Central State to shift the Kroger employees' and retirees' pensions out of the plan. The Kroger employees’ money makes up about 2.5 percent of the pension plan.

The pension plan’s trustees rejected the proposal within five days, the lawsuit said. The plaintiffs said that indicated they didn’t give it serious consideration. They want an independent outsider to consider their request – which they call “urgent” – to pull out of the plan. The proposal indicates that after June 15, Kroger and the Teamsters won’t be obligated to go ahead with the proposal.

“The Kroger participants will be trapped in a plan that is about to cut their benefits dramatically and still faces likely insolvency” if their pension benefits are not transferred elsewhere before then, they said in a news release.
“Kroger and the Teamsters are continuing to work together to address this situation,” Kroger spokesman Keith Dailey told me. “Kroger and the Teamsters have met and corresponded with Central States many times over the last 12 months. They have indicated a willingness to modify the transfer proposal if Central States does not think it is sufficient to protect the remaining non-Kroger participants. Thus far, Central States has not discussed any possible modifications with Kroger or the IBT.
“The best course for everyone would be for Central States to agree to the requested transfer. Kroger and the (Teamsters) continue to hope Central States Pension Fund trustees will consider it seriously. It fully protects pension benefits of our Kroger associates and it leaves the Central States Pension Fund no worse off.”
Some of Kroger’s employees got involved in the pension plan through a deal with the Teamsters that goes back to the 1970s, Dailey told me. Most Kroger retirees have pensions with dozens of other plans, many of which are sponsored by the Cincinnati-based supermarket giant.

The plan has been in decline over the years. In 1980 it had more than 11,000 employers. Now it has about 1,500. Much of that decline followed deregulation of the trucking industry, the lawsuit said. It also suffered $7.6 billion in investment losses in 2008 from the financial crisis.

April 20, 2016

One of the Nation's Largest Multi-employer Pension Plans Could Cut Pensions by 50 Percent

One of the nation’s largest pension funds could soon cut benefits for retirees


Members of the International Brotherhood of Teamsters and their supporters attend a rally outside the Capitol in Washington on April 14. The demonstrators protested a plan by the Central States Pension Fund to reduce payments to retirees. (Drew Angerer/Bloomberg)

April 20, 2016

Washington Post - More than a quarter of a million truckers, retirees and their families could soon see their pension benefits severely cut — even though their pension fund is still years away from running out of money.

Within the next few weeks, the Treasury Department is expected to announce a crucial decision on whether it will approve reductions to one of the country’s largest multi-employer pension plans.

The potential cuts are possible under legislation passed by Congress in 2014 that for the first time allowed financially distressed multi-employer plans to reduce benefits for retirees if it would improve the solvency of the fund. The law weakened federal protections that for more than 40 years shielded one of the last remaining pillars that workers could rely on for financial security in retirement.

For many workers, the promise of a guaranteed income stream for life — a benefit now nearly extinct for younger generations — was at times strong enough to convince them to sacrifice pay raises or other job opportunities. But after decades of challenges that left many pension funds in tough financial straits, some people are learning in retirement that the promises made to them may have to be broken.

The Central States Pension Fund, which handles the retirement benefits for current and former Teamster union truck drivers across various states including Texas, Michigan, Wisconsin, Missouri, New York and Minnesota, was the first plan to apply for reductions under the new law.

Consumer advocates watching the case say the move could encourage dozens of other pension plans across the country that are facing financial struggles to make similar cuts.
“This is going to be a national crisis for hundreds of thousands, and eventually millions, of retirees and their families,” said Karen Friedman, executive vice president of the Pension Rights Center.
Like many other pension plans, the Central States Pension Fund suffered heavy investment losses during the financial crisis that cut into the pool of money available to pay out benefits. While the stock market has recovered since then, the improvements were not enough to make up for the shortfall that grew as the number of companies contributing to the plan declined and the number of people retiring and collecting benefits increased, said Thomas Nyhan, executive director of the Central States Pension Fund.

That imbalance left the fund paying out $3.46 in pension benefits for every $1 it received from employers. The shortfall has resulted in the fund paying out $2 billion more in benefits than it receives in employer contributions each year.

If nothing is done, the fund could become insolvent by 2025, said Nyhan. And because of its size, the plan could overwhelm the Pension Benefit Guaranty Corporation, the insurance agency meant to shore up private pension funds, if it went under, Nyhan said.

The Central States Pension Fund pays out $2.8 billion a year in benefits, which would be reduced if the plan became insolvent. By comparison, the PBGC fund that backs multi-employer plans has roughly $2 billion in assets and is also projected to be insolvent by 2025.
“This was a very hard decision, a gut-wrenching decision,” Nyhan said, adding that he feared not taking any action could leave retirees with no pension at all. “It’s not a question of if there are going to be cuts. The question is where and when.”
If Treasury approves the fund’s proposal, then retirees could see their paychecks shrink by July 1. The move would give the fund at least a 50 percent chance of lasting for another 30 years as opposed to running out of cash in 10 years if no changes are made, Nyhan said. A decision is expected by May 7.


But opponents say there may be some negative consequences if the cuts are approved.
“It’s going to open the floodgates for other cuts,” said Friedman of the Pension Rights Center.
Out of the 10 million workers and retirees covered by multi-employer pension plans, roughly 1 million people are in plans that could run out of money over the next two decades, according to estimates from the PBGC. Already, three other pension plans that pay benefits to truck drivers and ironworkers have applied to the Treasury to have their pension benefits reduced.
 
The proposal introduced in September by Central States would cut benefits for current workers and retirees by 23 percent on average, though exact amounts would vary based on people’s age, health status and where they worked.
 
For many retirees, the losses may be much steeper.
 

September 2, 2015

The Case for Keeping Interest Rates as Low as Possible for as Long as Possible


A dangerously misleading idea threatens to derail the American economy

August 27, 2015

Vox - The US economy got some great news Thursday morning when revised numbers indicated that the economy grew 3.7 percent in the second quarter. That same report carried zero indication that inflation is getting out of hand, but nonetheless was greeted with speculation that it might induce the Federal Reserve to raise interest rates sooner rather than later. After all, good news indicates that the economy can survive without life support.

When you see a person in the hospital with oxygen tubes in her nose and a saline drip in her arm, you assume the doctors have done this for some good reason. Most likely, if the tubes were removed the patient's health would be in serious jeopardy. But all else being equal, having tubes stuck in you is a pretty crappy situation. It's uncomfortable, and it limits your mobility. As soon as it's safe, you'd want to pull the tubes out. Now that the emergency created by the 2008 financial crisis is over, some people are anxious to pull the tube out and let the patient get back to living a normal life.

But there's actually no reason to think low interest rates are a problem for the US economy. Low interest rates reduce the federal deficit, encourage entrepreneurship, and boost economic growth. As long as inflation stays low — and right now, it's extremely low and likely to stay that way for a long time — we should relax and enjoy the benefits.

The perverse urge to normalize

As of a couple of weeks ago, the overwhelming conventional wisdom was that at its next meeting in September the Federal Reserve would finally raise interest rates for the first time since house prices started to collapse more than seven years ago. Then the financial trauma coming out of Asia cast doubt on that. William Dudley, the influential president of the New York Fed, said recent events made a rate hike "less compelling," and, partly as a result, US markets have been soaring ever since.

But Dudley also said, "I really do hope we can raise interest rates this year," and, most of all, that there's no reason to be thinking about new efforts at monetary stimulus: "I’m a long way from quantitative easing. The US economy is performing quite well."

This central analytic mistake is repeated daily on financial television shows, on "finance Twitter," in the business press, and apparently in staff-level discussions in the Federal Reserve. The conceit is that raising interest rates is a good thing, and the Fed should do it as soon as possible. Debate is entirely focused on whether higher rates would be catastrophic. Any good economic news counts as a reason to think they wouldn't be and therefore should come sooner.

In order to make it seem more obvious that higher interest rates are good, proponents of higher interest rates have taken to calling higher interest rates "normalizing" monetary policy. Normal things are good, right? Who could be against normal?

The case for low interest rates

But this is both totally wrong and a remarkably recent idea.

June 12, 2015

The Pace of Healing in the Housing Market is Losing Steam

This Is the Housing Chart That Keeps One Economist Up at Night

June 12, 2015

Bloomberg - It’s the one chart that keeps Stan Humphries up at night.

A decade after U.S. home sales peaked, 15.4 percent of owners in the first quarter owed more on their mortgages than their properties were worth, according to a report Friday by Zillow Inc. While that’s down from a high of 31.4 percent in 2012, it’s still alarmingly above the 1 or 2 percent that marks a healthy market, said Humphries, the chief economist at the Seattle-based real-estate data provider. Worse yet: The pace of healing is losing steam.

Underwater and Still Above Normal
• Share of mortgages in negative equity has been halved in almost four years, but a long way from healthy

The blotch stains the economy by restraining the housing recovery and by preventing the job market from becoming even more vigorous. It also will probably exacerbate wealth inequality for years to come as homes valued in the bottom third of the market are more likely to be underwater.
“There’s a large swath of the housing market which could become quite static, which creates real long-term problems,” Humphries said.
The share of mortgage borrowers underwater in the first quarter was down 3.4 percentage points from 18.8 percent at the same time last year, according to the Zillow data. That’s a marked slowdown in the pace of improvement from the 6.6 point drop in the 12 months through March 2014. Just over half the owners were 20 percent or more away from breaking even.
The problem “was kind of on a glide-slope to fade away and it’s now circling the airport,” said Humphries.
Home Appreciation

While the healthiest way for the underwater mortgages to heal is through home-price appreciation, those increases are diminishing. Residential property values nationally rose 4.14 percent in March from the prior year, according to the S&P/Case-Shiller index. The gauge has decelerated each month since the end of 2013, when it climbed 10.8 percent.
“I expect a more moderate pace of home-price appreciation,” said Greg McBride, senior financial analyst for Bankrate Inc. in North Palm Beach, Florida. Therefore, the progress in rebuilding home equity “is unlikely to come as quickly in the next three years as it has in the last three.”
The prospect of having so many properties lingering underwater, probably for another five or six years, is what unsettles Humphries.
“The problem you could be creating is 15 to 20 percent of the housing stock becomes non-tradeable, which means inventory shortages continue, prices remain very spiky because liquidity is thin, and foreclosures remain very high,” he said.
Less Spending

People with no equity in their homes also have little spending power to renovate them, devaluing the stock further, according to Nicolas Retsinas, director emeritus of Harvard University’s Joint Center for Housing Studies in Cambridge, Massachusetts, and a member of the board of directors at Freddie Mac.

June 7, 2015

$265 Billion in Home Equity Lines of Credit (HELOCs) Will Enter the Repayment Period in the Next Few Years; 10 Million HELOCs in Default Will Be a Downward Drag on America's Housing Recovery for Years to Come

The $265 Billion Wave That's About to Crush Homeowners

June 4, 2015

Credit.com - Millions of consumers will have to absorb a major hit to their household budget in the coming months. About $265 billion in home equity lines of credit (HELOCs) will enter the repayment period in the next few years, according to a study from Experian, and consumers may see their monthly payments spike — in some cases, triple or quadruple what they previously paid.

HELOC originations soared from 2005 up until the start of the housing crisis, and because many HELOCs enter the repayment phase after 10 years, these billions of dollars in outstanding credit balances are just now coming due. This wave of HELOC resets is expected to significantly stress borrowers' finances and the lending industry.
"This analysis is critical as we want to not only help lenders prepare and understand the payment stress of their borrowers, but also give consumers an opportunity to understand what the impact may be to their financial status and how to be better prepared for it," said Michele Raneri, Experian's vice president of analytics and business development, in a statement about the study.
HELOCs are generally divided into two periods: draw and repayment. During the draw period, consumers can use the line of credit while making minimum, interest-only payments. Once the HELOC resets, consumers can no longer borrow from that line of credit, and they must restore the equity they haven't yet repaid.
"Instead of using it like a line of credit, borrowing and then repaying the loan to restore the home equity that had been tapped into, most people simply took the maximum amount in cash and never tried to pay down the outstanding amount for the entire 10-year period," said Charles Phelan, a debt-relief consultant who specializes in HELOC negotiation, in an email.
He contributes content on the topic to Credit.com.
"In effect, most existing HELOCs are therefore like a huge credit card debt that has been at the maximum limit for years, with only interest expense being paid each month to keep the balance the same and not reduce it."
How much your payment increases depends on many things, like the interest rate and the length of the repayment period — a shorter repayment period generally translates into a larger increase in payment. Some HELOCs have no repayment period and require a lump-sum repayment when the draw period ends.

The HELOCs that are coming due were opened in very different economic times, under the impression that home values would continue to rise. Because that didn't happen, borrowers may not be prepared to handle this significant change to their finances.
"A lucky few will be able to absorb the new high monthly payment without defaulting and thereby risking foreclosure, and some will have sufficient equity to obtain a traditional refinance to a new single mortgage," Phelan wrote. "For a majority of homeowners with HELOCs, however, options are limited due to real estate prices having dropped to the point where the most HELOCs are not covered by equity. This blocks people from refinancing to a single new mortgage at a more reasonable payment level."
Even if refinancing is an option, it requires the borrower to have great credit. Phelan said borrowers without the ability to refinance can look into government loan-modification programs, Chapter 13 bankruptcy or settling the second lien, but he expects HELOC defaults to skyrocket. No matter how you plan to address your HELOC reset, it's crucial to have a grasp on your credit standing so you can better research your options for managing repayment and how those options will impact your credit. 
"With more than 10 million of these contracts having been issued during 2005-2008, a tsunami of defaults is likely and will be a downward drag on America's housing recovery for years to come," Phelan wrote.
If you took out a HELOC between 2005 and 2008 and you're not sure what you'll be facing when the HELOC resets, it's time to look at your agreement and understand what you're dealing with. Simply by calling your lender, you can get a handle on the situation and prepare to absorb this shock to your finances.

May 15, 2015

The Average U.S. Household Income Versus the Average Federal Employee's Salary

House and Senate members should only receive the median U.S. annual salary so that they are a more equal representation of The People Of The United States. Same for all government officials. Mayors should receive the city median income. State reps, as well as governors, the state median. There are others as well. I think this would really fix at least a couple of the problems our government has. - Josh J, March 11, 2015

How much do Americans earn? What is the average US income and other income figures

By

Breaking down US household income (this is combined household, not individual income) by category presents a clearer picture:

us-household-income
Source:  US Census

20.8 percent of US households make $100,000 or more. Only 4.3 percent make more than $200,000 and roughly 2 percent make more than $250,000.  Given all the ads you see on network TV you would think that every other US household was pulling in $200,000 a year given the kind of products that are pushed.  Of course most of the goods bought in the last decade were financed with massive debt and not actual saved wealth.

Where did income grow?

US income growth has been absent for most households.  In fact, over the last four decades most of the real income growth has occurred for the top 10 percent of US households:

income percentile

`The typical family barely saw any real income growth and that is why many feel a true pinch to their wallet.  Yet household incomes for earners in the top 10 percent saw real sizeable growth over the last four decades.

In comparison, the average individual income for federal employees as of September 2012 was nearly $78,500. In a household with two wage earners working for the federal government, the average household income would be $157,000, $106,500 more than the average U.S. household income. The Office of Personnel Management reported that as of September 2012, the average salary for a full-time, permanent, non-seasonal position was $78,467. The comparable figure for December 2010 was $76,701. The median salary — the point at which half are above and half are below — is now $74,714, up from $69,550 in 2010. Local and State government wages are comparable to federal wages in many areas through the United States. In others words, some government employees are retiring as millionaires after 20 years (law enforcement and firefighters) or 30 years of service.

March 14, 2015

Only Government, Government Contractors, Wall Street, International Mega Corporations, Military Industrial Complex, Pharmaceutical Industrial Complex, and Virtual Business Monopolies Like Google, Microsoft and Amazon Can Pay Workers Wages Unrelated to the Value of Their Work

Restaurants in Seattle Going Dark as $15 an Hour Minimum Wage Looms

Inferior food at higher prices delivered by over-worked servers during restricted hours: recipe for failure. 

March 14, 2015

PJ Media - I like this simple, elegant explanation from Reason’s Ronald Bailey about the value of labor and the minimum wage:
If all other factors remain equal, the higher the price of a good, the less people will demand it. That’s the law of demand, a fundamental idea in economics. And yet there is no shortage of politicians, pundits, policy wonks, and members of the public who insist that raising the price of labor will not have the effect of lessening the demand for workers. In his 2014 State of the Union Address, for example, President Barack Obama called on Congress to raise the national minimum wage from $7.25 to $10.10 an hour. He argued that increasing the minimum wage would “grow the economy for everyone” by giving “businesses customers with more spending money.”
A January 2015 working paper by two economists, Robert Pollin and Jeanette Wicks-Lim at the Political Economy Research Institute at the University of Massachusetts Amherst, claims that raising the minimum wage of fast food workers to $15 per hour over a four-year transition period would not necessarily result in “shedding jobs.” The two acknowledge that the “raising the price of anything will reduce demand for that thing, all else equal.” But they believe they’ve found a way to “relax” the all-else-being-equal part, at least as far as the wages of fast food workers go. Pollin and Wicks-Lim argue that “the fast-food industry could fully absorb these wage bill increases through a combination of turnover reductions; trend increases in sales growth; and modest annual price increases over the four-year period.” They further claim that a $15/hour minimum wage would not result in lower profits or the reallocation of funds away from other operations, such as marketing. Amazing.
Seattle is going to put that theory to a real world test. Starting April 1, businesses in the city will be forced to raise the minimum wage to $11 an hour, reaching $15 an hour by 2017 for large businesses and 2019 for smaller companies. There are allowances if a business offers health insurance benefits, but all businesses will be paying employees $15 an hour in salary, tips, or benefits by 2021.

March 2, 2015

Feds Targeting Personal Retirement Accounts

White House looking to creep into 401(k)s

February 28, 2015

Last Monday, with Sen. Elizabeth Warren (D-Mass.) at his side, President Obama attacked Wall Street, again, for essentially helping in what the federal government and businesses can no longer provide — a decent retirement.

Under the false pretense of calling for new and tougher so-called fiduciary standards for financial brokers, advisers and retirement plan representatives, the White House once again horned in on Wall Street’s compensation formulas.

However, what the president surely knows is that a vast majority of retirement plans — IRAs and 401(k)s — are in simple fee-based products like mutual funds. The commission-based accounts are for those who prefer to direct their brokers in certain purchases inside some of their retirement products.

The key to the White House’s interference is in its nuanced language.

February 27, 2015

Groundbreaking Ruling on Public Sector Pension Plans by Detroit Bankruptcy Judge Could Lead to Other States and Municipalities Cutting Retirees’ Pensions, Freezing Existing Pension Plans, and Shifting Workers into New Plans

Cracks Starting to Appear in Public Pensions’ Armor

February 25, 2015

New York Times - First in Detroit, then in Stockton, Calif., and now in New Jersey, judges and other top officials are challenging the widespread belief that public pensions are untouchable.

Gov. Chris Christie of New Jersey delivered the latest blow on Tuesday, when he proposed to freeze that state’s public pension plans and move workers into new ones intended not to overwhelm future budgets or impose open-ended demands on taxpayers.

The first crack came in Detroit, where a judge ruled that public pensions could, in fact, be reduced, at least in bankruptcy. Then, just a few weeks ago, an opinion by the bankruptcy judge for Stockton, which emerged from Chapter 9 on Wednesday, called California’s mighty public pension system, Calpers, a bully for insisting in court that pension cuts were wholly out of the question.

Such dogma “encourages dysfunctional strategies,” wrote the judge, Christopher Klein, chief judge of the United States Bankruptcy Court for the Eastern District of California. He said Calpers’s legal arguments were invalid, and he concluded that it lacked standing to dominate the courtroom discussion the way it had. Stockton did not even seek permission to freeze its pension plans, but the judge nevertheless wrote that it was entitled to do so and went on to cite steps that struggling cities in general should take to trim their pension costs legally.

February 2, 2015

Obama to Seek New Taxes on Trillions of Dollars in Profits Accumulated Overseas by U.S. Companies But If He Were Serious About Closing Loopholes, He Would Have Targeted Reform When Democrats Controlled the House And Senate


January 29, 2015

McCain Calls Protesters at Senate Armed Services Hearing “Low-life Scum”


Right or wrong, they exercised their right to express their opinion, and that is spot on.
"Today, America would be outraged if U.N. troops entered Los Angeles to restore order [referring to the 1991 LA Riot]. Tomorrow they will be grateful! This is especially true if they were told that there were an outside threat from beyond [i.e., an "extraterrestrial" invasion], whether real or promulgated, that threatened our very existence. It is then that all peoples of the world will plead to deliver them from this evil. The one thing every man fears is the unknown. When presented with this scenario, individual rights will be willingly relinquished for the guarantee of their well-being granted to them by the World Government." - Dr. Henry Kissinger, Bilderberger Conference, Evians, France 

January 18, 2015

Mortgage Insurance Companies Seek Money from Former Homeowners to Recover Their Loses from Foreclosures

Homeowners billed for houses lost in foreclosure


New England Center for Investigative Reporting - When Guillermo Galindo lost his two-family Revere home to foreclosure in 2009, the soft-spoken Colombian thought he had finally freed himself from the flood of threatening collection letters from his lender and a ballooning, untenable debt.

All of his savings, scraped together over years delivering medicine for local pharmacies, were gone, along with the home he bought in 2005 for $410,000. Devastated, the 54-year-old immigrant, along with his wife and 3-year-old daughter, packed their belongings and moved into a small apartment, hoping to rebuild.

But that hope evaporated in a matter of months, when Galindo received a letter from a lawyer saying he owed $136,547 on the family home he’d left behind.

The lawyer represented a mortgage insurance company that Galindo had paid premiums to for years. He’d never given his insurance policy much thought — it was just something he needed to buy to qualify for a mortgage, since he couldn’t afford a big down payment. He thought it would help him if he got in a bind.

Too late, Galindo realized that the policy protected only the bank, and nothing prevented the insurer from coming after him for losses related to the foreclosure on his former home in Revere.

January 11, 2015

Why Your Mortgage Interest Isn't Actually Tax Deductible

Why Your Mortgage Interest Tax Deduction Doesn't Really Help Much


The Motley Fool - No tax deduction is more misunderstood than the mortgage interest tax deduction. By law, taxpayers can deduct interest paid on their mortgage, but most middle-class taxpayers save little or nothing at all from the mortgage interest tax deduction.

In fact, the mortgage interest tax deduction is more for the benefit of millionaires than it is the average American.

How the mortgage interest deduction works